
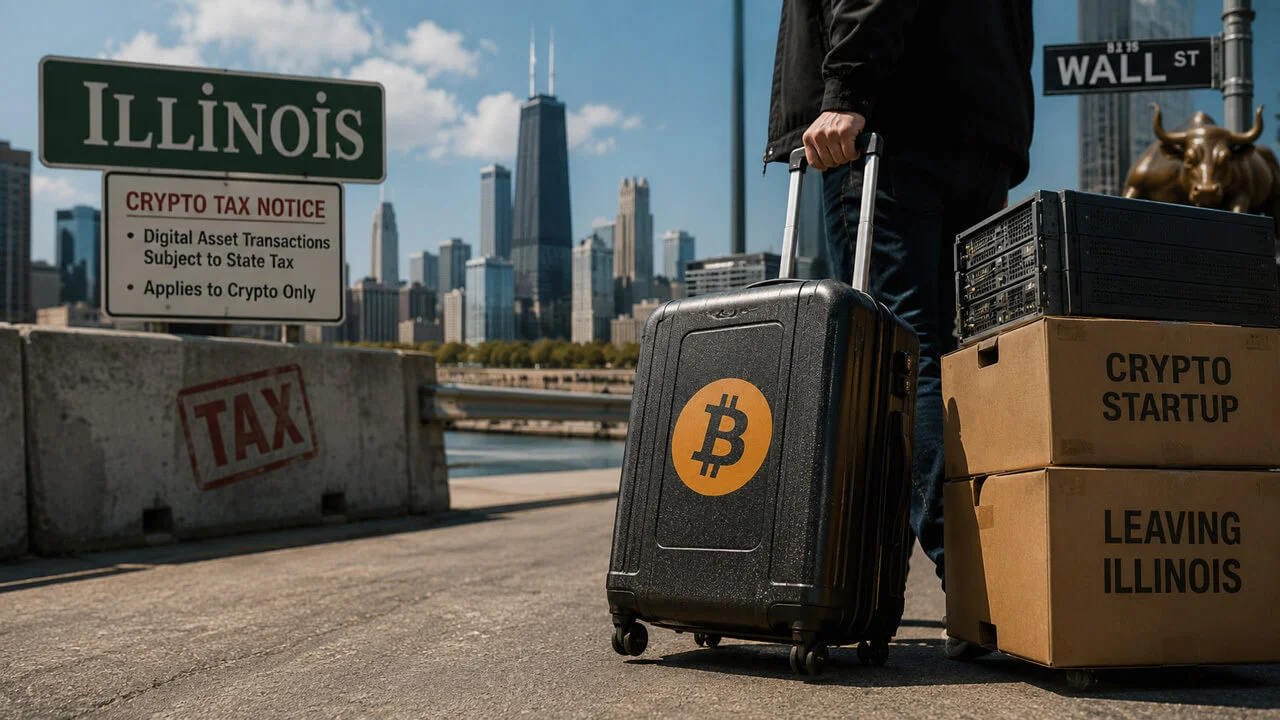
Cryptocurrency advocates have launched a significant legal challenge against Illinois, arguing that the state’s digital asset tax violates fundamental constitutional principles and creates unfair financial burdens on blockchain investors and traders. This crypto lawsuit represents a pivotal moment in the ongoing battle between digital currency enthusiasts and state governments seeking to regulate and tax cryptocurrency transactions. The case highlights the growing tension between innovation in the blockchain industry and governmental attempts to establish regulatory frameworks that protect state revenues while ensuring compliance with tax obligations.
The Illinois digital asset tax, also known as the Digital Assets Tax Act, has become one of the most contentious pieces of legislation in the cryptocurrency sector. Since its introduction, crypto advocates and digital asset holders have expressed serious concerns about its constitutionality, feasibility, and potential impact on the broader cryptocurrency market. The lawsuit filed by various blockchain organizations and individual investors argues that the tax creates an unconstitutional burden on interstate commerce and violates the Fourth Amendment by requiring excessive record-keeping and reporting requirements. This legal battle is not simply about taxation—it’s about the fundamental right to transact in digital currencies without excessive government intrusion.
Understanding this lawsuit is crucial for anyone involved in cryptocurrency trading, blockchain development, or digital asset investment. The outcome could set precedents for how other states approach crypto taxation and regulatory oversight. Whether you’re a casual cryptocurrency investor or a serious trader, the implications of this case could directly affect your ability to engage in digital asset transactions without facing excessive compliance costs or constitutional violations.
The Illinois Digital Asset Tax: What You Need to Know
Illinois introduced its digital asset tax as part of broader efforts to capture tax revenue from the growing cryptocurrency market. The legislation specifically targets individuals and entities that hold or trade digital currencies within the state, imposing what proponents claim is a modest tax on certain blockchain transactions. However, crypto advocates argue that the law is far more problematic than state officials acknowledge, creating compliance nightmares and imposing unreasonable reporting burdens on residents.
The tax mechanism requires individuals to report detailed information about their cryptocurrency holdings, transaction history, and transfers. According to digital asset experts analyzing the law, the reporting requirements are particularly onerous because they demand comprehensive tracking of every blockchain transaction, regardless of whether the transaction resulted in a gain or loss. This level of scrutiny has prompted cryptocurrency advocates to question whether Illinois lawmakers fully understood the technical complexities of the digital currency ecosystem or the practical implications of such sweeping reporting mandates.
One critical concern raised by blockchain professionals is that the tax treats digital assets differently than traditional investments, creating what many argue is discriminatory treatment. While traditional stock transactions face standard capital gains taxation, the Illinois approach to cryptocurrency taxation imposes additional administrative burdens that don’t apply to conventional securities trading. This disparity forms one of the central arguments in the crypto lawsuit, with digital asset advocates contending that the state has violated equal protection principles by singling out blockchain-based investments for harsher treatment.
Who Is Suing Illinois: The Coalition of Crypto Advocates
The lawsuit against Illinois has been brought forward by a diverse coalition of cryptocurrency advocates, organizations, and individual investors who share common concerns about the state’s approach to digital asset taxation. This group includes prominent blockchain advocacy organizations, cryptocurrency exchanges operating in Illinois, individual traders, and technology companies focused on digital currency infrastructure. Their united front demonstrates the breadth of opposition to Illinois’s digital asset tax across different segments of the cryptocurrency community.
Several major crypto organizations have thrown their support behind the legal challenge, arguing that the tax represents governmental overreach into the blockchain space. These cryptocurrency advocates have invested significant resources into fighting the legislation, viewing it as a threat not only to their business interests but also to the principles of financial innovation and decentralization that underpin the digital currency movement. Individual plaintiffs in the case include Illinois residents who hold cryptocurrency and have been directly affected by the reporting and taxation requirements imposed by the state.
The diversity of the plaintiff group is significant because it underscores that opposition to the Illinois digital asset tax transcends narrow business interests. While some plaintiffs are commercial entities with millions of dollars at stake, others are individual cryptocurrency enthusiasts who simply want the freedom to participate in the blockchain economy without excessive governmental interference. This broad coalition has amplified the message that the tax is fundamentally problematic, not just inconvenient, and that it threatens the viability of digital asset participation for ordinary Illinois residents.
Constitutional Arguments Against the Digital Asset Tax
The legal challenge mounted by crypto advocates against Illinois rests on several substantial constitutional arguments that go to the heart of governmental authority and individual rights. The primary constitutional concern centers on whether Illinois has exceeded its authority to tax digital currencies in ways that violate the Commerce Clause of the United States Constitution. Cryptocurrency advocates argue that the tax creates an unconstitutional burden on interstate commerce by imposing requirements that effectively tax economic activity involving blockchain transactions conducted across state lines.
Another critical constitutional argument involves the Fourth Amendment right to privacy. Blockchain experts and digital asset attorneys have contended that the reporting requirements demanded by Illinois constitute an unreasonable search and seizure of financial information. The law requires individuals to disclose exhaustive details about their cryptocurrency holdings and transactions, creating what crypto advocates describe as a surveillance regime that lacks appropriate limitations or protections for financial privacy. This argument suggests that while states have legitimate taxation authority, the methods they employ cannot violate constitutional protections against unreasonable invasions of privacy.
Digital currency lawyers have also raised Fifth Amendment arguments, contending that the self-incrimination aspects of mandatory reporting create constitutional problems. Because cryptocurrency exists in a regulatory gray zone in many jurisdictions, compelled disclosure of detailed blockchain transaction information could potentially expose individuals to criminal liability for activities that may not be illegal under federal law but could be prosecuted under state statutes. This creates a perverse incentive structure where residents must choose between complying with Illinois’s digital asset tax requirements or risking self-incrimination, a choice that cryptocurrency advocates argue is fundamentally unconstitutional.
The Impact on Cryptocurrency Users and the Blockchain Economy
For ordinary cryptocurrency users in Illinois, the digital asset tax creates practical challenges that extend far beyond simple financial burden. Digital currency enthusiasts who wish to engage in trading, staking, or other blockchain activities must navigate complex reporting requirements that demand technical knowledge many ordinary investors simply don’t possess. This creates a significant barrier to entry for individuals interested in participating in the cryptocurrency market, potentially stifling innovation and adoption of blockchain technology within the state.
The crypto lawsuit raises important questions about how aggressive digital asset taxation might reshape investment behavior. Many cryptocurrency advocates argue that Illinois’s approach will simply drive digital currency activity underground or to other jurisdictions with friendlier regulatory environments. Rather than generating meaningful tax revenue, the law could ultimately reduce tax collections by encouraging residents to move their blockchain activities and investments to states with less burdensome cryptocurrency taxation policies. This outcome would undermine the state’s stated objective of capturing tax revenue while simultaneously harming the Illinois economy by discouraging digital asset innovation and investment.
Small businesses and startups in the blockchain sector have also raised concerns about the impact of Illinois’s digital asset tax on their ability to operate and expand. The compliance costs associated with tracking and reporting every cryptocurrency transaction create fixed expenses that disproportionately burden smaller companies. Crypto advocates working in startup environments have warned that the tax could accelerate the exodus of blockchain talent and innovation from Illinois to more permissive jurisdictions, ultimately weakening the state’s position in the rapidly growing digital currency economy.
Implications for State Regulation of Digital Assets
The crypto lawsuit against Illinois will likely have far-reaching implications for how other states approach digital asset taxation and regulation. If cryptocurrency advocates prevail in their constitutional challenge, it could establish important legal precedents limiting state authority to impose burdensome reporting requirements on blockchain activities. Conversely, if Illinois prevails, it could embolden other states to implement similarly aggressive digital currency tax policies, potentially leading to a patchwork of conflicting cryptocurrency regulations across different jurisdictions.
The outcome of this case will substantially influence how policymakers approach blockchain regulation moving forward. States considering their own digital asset tax legislation will closely monitor the Illinois case to understand which regulatory approaches survive constitutional scrutiny and which face legal vulnerability. This makes the lawsuit not merely a state-level dispute but a critical test case for how American government will ultimately regulate and tax the cryptocurrency sector at the state level.
Cryptocurrency advocates argue that the case presents an opportunity for courts to establish clearer constitutional boundaries around state taxation authority over digital currencies. Rather than allowing individual states to experiment with increasingly aggressive digital asset taxes, a favorable ruling for the plaintiffs could establish national standards that protect participants in the blockchain economy while still allowing states reasonable taxation authority. This balanced approach would provide clarity and consistency that benefits both cryptocurrency businesses and state governments seeking legitimate tax revenue.
The Broader Context of Cryptocurrency Regulation
The Illinois digital asset tax lawsuit must be understood within the broader context of how American government is grappling with regulating the cryptocurrency sector. At the federal level, regulators have struggled to develop coherent frameworks for overseeing blockchain activities, creating a regulatory vacuum that some states have attempted to fill with their own legislation. The result has been an inconsistent patchwork of state-level digital currency regulations that often contradict each other and create compliance nightmares for businesses operating across multiple jurisdictions.
Crypto advocates have consistently argued that state-by-state regulation of digital assets is fundamentally incompatible with the borderless nature of blockchain technology. Digital currencies by their nature don’t respect state boundaries, making it difficult for cryptocurrency businesses to comply with jurisdiction-specific requirements. The Illinois case highlights this central tension: how can states effectively tax and regulate digital currency activities that inherently transcend geographical boundaries? Blockchain experts believe this structural incompatibility is a fatal flaw in Illinois’s digital asset tax approach.
Federal regulators and cryptocurrency policymakers have increasingly recognized the need for national standards to govern digital asset taxation and regulation. The Illinois lawsuit may ultimately provide judicial impetus for federal lawmakers to preempt state-level digital currency taxation and establish uniform national standards. Crypto advocates argue that such federal action would benefit everyone: states would have clear guidance on what digital asset taxation approaches are permissible, and cryptocurrency businesses would gain regulatory certainty and the ability to operate consistently across state lines.
What This Means for Illinois Residents and Investors
For Illinois residents who hold cryptocurrency or engage in blockchain activities, the digital asset tax has created immediate practical challenges. Those subject to the tax must either comply with burdensome reporting requirements or face potential penalties and legal consequences. The uncertainty surrounding the tax’s constitutionality creates additional complications, as Illinois residents cannot be confident whether their cryptocurrency activities are taxable or what their ultimate tax liability might be under the law.
Digital asset investors in Illinois have faced particular challenges in planning their cryptocurrency portfolios. Tax planning is a standard practice for investors managing traditional securities, but digital currency investors in Illinois must consider not only federal capital gains taxation but also the state’s additional digital asset tax requirements. This added complexity makes cryptocurrency investing less attractive for Illinois residents compared to residents of other states without similar digital asset taxation schemes, potentially depressing investment in blockchain technologies within the state.
Individual cryptocurrency advocates have found themselves at the center of broader debates about government authority and individual rights. Some Illinois residents supporting the lawsuit view it as a matter of principle—a fight against governmental overreach into financial privacy. Others focus more narrowly on practical concerns about tax compliance costs and burdensome reporting. Regardless of their specific motivations, these individuals have helped bring visibility to concerns that many in the crypto community share about aggressive digital asset regulation.
The Path Forward: What Happens Next
The cryptocurrency lawsuit against Illinois will proceed through the court system, likely taking years to reach final resolution. Crypto advocates have prepared comprehensive legal briefs outlining their constitutional arguments, and the state of Illinois has mounted a vigorous defense of its digital asset taxation authority. The case will likely progress through multiple stages, potentially reaching appellate courts and possibly the Illinois Supreme Court, depending on how the litigation develops.
Throughout this legal process, digital currency participants and businesses will need to navigate the uncertain regulatory environment created by the unenforced and legally challenged digital asset tax. Some cryptocurrency advocates have advocated for a temporary moratorium on the tax’s enforcement pending judicial resolution of constitutional questions, though Illinois state officials have resisted such suggestions. This has left blockchain businesses and individual investors in limbo, uncertain about their compliance obligations and potential tax liabilities.
Crypto advocates are also pursuing legislative solutions in parallel with their litigation strategy. Some have engaged with Illinois lawmakers to discuss reforming the digital asset tax in ways that would address constitutional concerns while still allowing the state to collect legitimate tax revenue from cryptocurrency transactions. These discussions highlight that opposition to Illinois’s current digital asset tax doesn’t necessarily reflect opposition to all cryptocurrency taxation, but rather opposition to the specific form and structure of Illinois’s approach.
Conclusion
The lawsuit brought by crypto advocates against Illinois over its digital asset tax represents a pivotal moment in the ongoing evolution of American cryptocurrency regulation. The case raises fundamental questions about governmental authority, constitutional limitations on taxation, and the proper role of state governments in regulating blockchain technology. Whether through judicial victory or legislative reform, the resolution of this conflict will shape how digital currencies are taxed and regulated in Illinois and potentially influence approaches to cryptocurrency regulation across the United States.
Cryptocurrency advocates have mounted a serious constitutional challenge to Illinois’s digital asset tax, arguing that the law violates Commerce Clause protections, Fourth Amendment privacy rights, and other fundamental constitutional principles. The breadth of the plaintiff coalition—spanning from major blockchain organizations to individual digital currency enthusiasts—demonstrates the widespread concern about the tax’s impact on cryptocurrency participation and innovation. As this legal battle progresses, both crypto participants and state policymakers will be watching closely for guidance on how American government will ultimately balance the legitimate interests of digital asset taxation with the constitutional rights and practical realities of blockchain technology.
The ultimate outcome of this cryptocurrency lawsuit will influence not only Illinois’s future regulatory approach to digital assets but also serve as a template—positive or negative—for other states considering their own blockchain taxation policies. The case underscores the need for coordinated federal guidance on cryptocurrency regulation, as the state-by-state approach has proven unwieldy and potentially unconstitutional. Whether through courts, legislatures, or federal regulators, American government will eventually need to develop coherent frameworks for taxing and regulating digital currencies in ways that respect both constitutional limitations and the legitimate interests of states in collecting tax revenue.
Frequently Asked Questions
Q1: What exactly is the Illinois digital asset tax, and who does it apply to?
The Illinois Digital Assets Tax Act is state legislation designed to impose taxation on digital currency transactions and holdings within the state. The tax applies to Illinois residents who hold cryptocurrency, trade digital assets, or engage in other blockchain activities.
Q2: What are the main constitutional arguments made by crypto advocates in their lawsuit?
Cryptocurrency advocates base their legal challenge on several constitutional grounds. The primary argument centers on violation of the Commerce Clause, contending that the tax creates an unconstitutional burden on interstate commerce by attempting to tax blockchain transactions conducted across state lines. compared to traditional security holders.
Q3: How could this lawsuit affect other states’ approaches to digital asset taxation?
The outcome of the Illinois digital asset tax lawsuit will likely establish important legal precedents that guide how other states develop their own cryptocurrency taxation policies. If crypto advocates prevail, the ruling will establish constitutional limitations on aggressive digital asset taxation and reporting requirements, making it harder for other states to implement similar laws.
Q4: What practical impact has the digital asset tax had on Illinois residents and cryptocurrency businesses?
The digital asset tax has created significant practical challenges for Illinois residents and blockchain businesses. Individual cryptocurrency investors must navigate complex reporting requirements that demand extensive technical knowledge about blockchain transactions and holdings.
Q5: Is there any possibility that Illinois will reform or repeal the digital asset tax without waiting for the lawsuit’s resolution?
While the lawsuit proceeds through the courts, there remains some possibility that Illinois lawmakers could reform or repeal the digital asset tax through legislative action. Some cryptocurrency advocates have engaged with state legislators to discuss modifications that would address constitutional concerns while still allowing Illinois to collect tax revenue from blockchain activities.
