
The global conversation surrounding stablecoin regulation has taken center stage in financial policy discussions, yet the narrative presented to the public often masks a deeper, more strategic agenda. While regulators and policymakers consistently frame cryptocurrency regulations as essential for consumer protection, the true driver behind these stringent policies appears to be something far more consequential: the preservation of the U.S. dollar’s unchallenged dominance in global finance.
Stablecoins, which are digital currencies pegged to the value of traditional assets like the dollar, have emerged as one of the fastest-growing segments within the cryptocurrency market. These tokens promise efficiency, accessibility, and reduced transaction costs for billions of people worldwide. However, as their adoption accelerates, regulatory bodies across developed nations have begun implementing increasingly restrictive frameworks. The stated objective remains consistent: protecting consumers from volatility and fraud. Yet a closer examination of the regulatory landscape reveals a far more nuanced picture—one where monetary policy and financial sovereignty play starring roles.
This article explores the intersection of stablecoin policy, digital currency regulation, and financial geopolitics, revealing how the push for stricter oversight of stablecoins is fundamentally intertwined with concerns about the dollar’s long-term viability as the world’s reserve currency. By understanding this connection, we gain insight into why certain regulations are prioritized while others remain conspicuously absent, and what the future of digital asset regulation might look like in a world increasingly moving toward financial decentralization.
The Real Motive Behind Stablecoin Regulation
The Regulatory Narrative
Governments and financial regulators have built a compelling case for why cryptocurrency market oversight is necessary. They point to consumer losses from exchange hacks, fraud schemes, and market manipulation. They cite the need for financial stability and protection against money laundering. These concerns are not entirely fabricated—the digital currency space has indeed experienced significant incidents that have harmed investors. However, this narrative conveniently overlooks the regulatory community’s primary concern: stablecoins pose an existential threat to dollar hegemony.
The distinction is crucial. True consumer protection regulation would focus narrowly on fraud prevention, disclosure requirements, and custody safeguards. Instead, the regulations being proposed and implemented globally address far broader issues: transaction limits, reserve requirements, and restrictions on stablecoin issuance that extend well beyond what would be necessary for investor safety. These measures suggest that regulators are thinking about something bigger—the systemic implications of a world where the dollar is no longer the exclusive medium of international commerce.
The Dollar’s Unique Position in Global Finance
To understand why stablecoin policy has become so contentious, one must first appreciate the extraordinary privilege the U.S. dollar enjoys in the global financial system. Since the end of the Bretton Woods system in 1971, the dollar has functioned as the world’s de facto reserve currency, a status that generates enormous benefits for the United States economy and government. This monetary privilege allows America to borrow at lower interest rates, export inflation to other nations, and maintain geopolitical leverage through financial sanctions and capital controls.
Digital payment systems based on blockchain technology inherently threaten this arrangement. A widely adopted stablecoin ecosystem would create an alternative financial infrastructure that operates outside traditional banking channels and regulatory oversight. More importantly, it would enable direct peer-to-peer transactions across borders without intermediaries—a capability that could fundamentally alter how international financial settlement works. If businesses and consumers could easily transact in stablecoins rather than dollars, the demand for dollar-denominated assets would decline, weakening American financial power.
How Stablecoins Challenge Dollar Dominance
The Mechanism of Monetary Displacement
Stablecoin adoption threatens the dollar not through direct currency replacement, but through the gradual displacement of dollar usage in specific economic niches. Consider international trade: currently, a Chinese exporter selling goods to a Brazilian importer must convert their sale to dollars, move those dollars through correspondent banking networks, and then convert back to Brazilian reals. This process involves multiple intermediaries, fees, and time delays. A stablecoin-based transaction would eliminate these friction points entirely.
This efficiency advantage becomes exponentially more valuable as digital asset networks scale. Once stablecoins achieve critical mass in emerging markets—regions where the dollar’s grip on commerce is less entrenched—they could rapidly absorb a meaningful portion of transaction volume that would otherwise flow through dollar-based systems. From a regulatory perspective, this represents an intolerable scenario. The Federal Reserve and Treasury Department cannot tolerate a parallel financial infrastructure that operates outside their control.
The Geopolitical Dimension
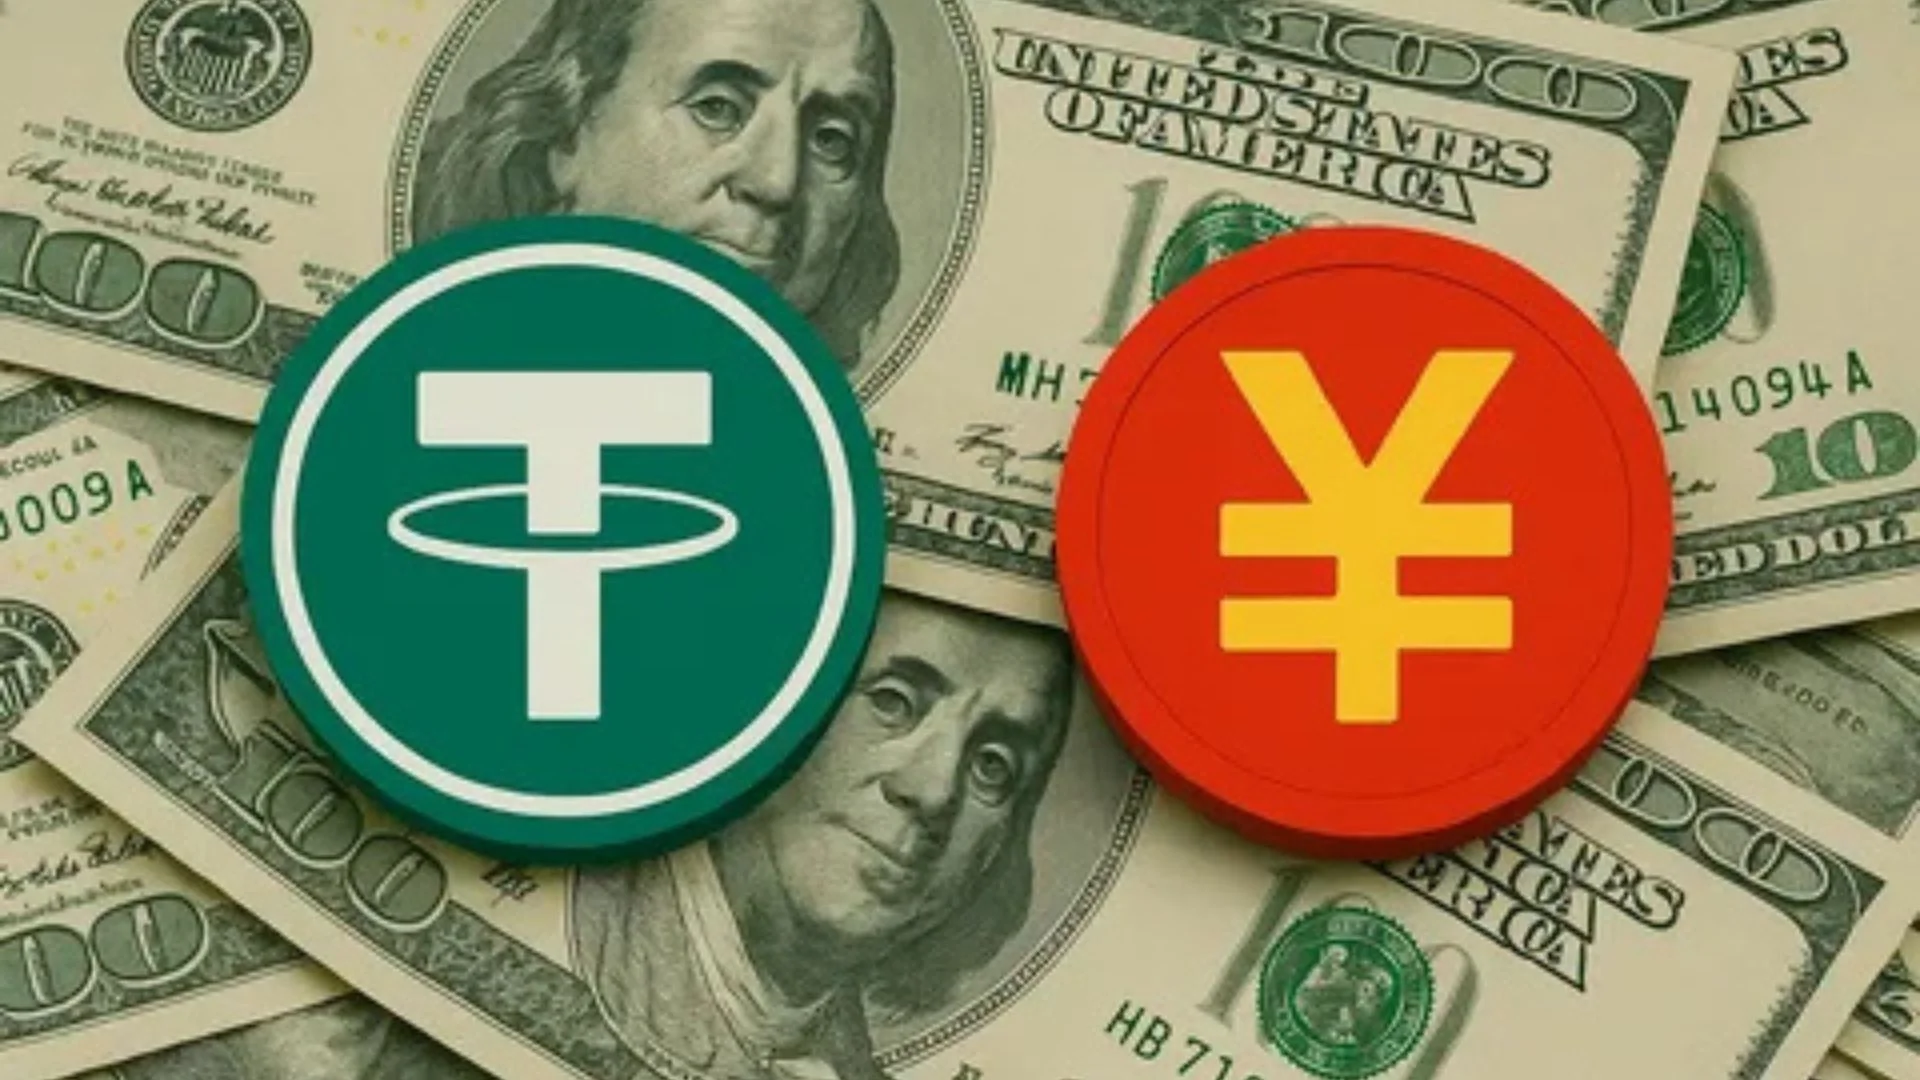
The regulatory push against stablecoins also reflects deeper anxieties about geopolitical competition. China’s development of the digital yuan, the European Union’s exploration of a digital euro, and numerous emerging market digital currency initiatives all suggest that other powers are contemplating life beyond dollar dependence. If the United States allows private stablecoins to flourish unregulated, it inadvertently facilitates the very ecosystem that could enable other nations to build their own alternative payment networks.
By tightening cryptocurrency regulation, American and Western regulators effectively maintain their monopoly over financial infrastructure. They ensure that any digital currency system powerful enough to matter remains under state control, compatible with existing capital controls, and subject to sanctions regimes. This is not consumer protection—it is financial sovereignty protection.
The Selective Nature of Regulatory Enforcement
Inconsistencies That Reveal True Priorities
If genuine consumer protection were the primary regulatory motivation, we would expect to see consistent enforcement across all areas of financial risk. Yet this is precisely what we do not observe. Cryptocurrency exchanges operate in many jurisdictions with minimal licensing requirements, while traditional financial institutions that engage in far riskier behavior face comparatively light oversight. Banks routinely engage in practices—like fractional reserve lending, derivatives speculation, and interconnected risk-taking—that pose systemic risks far exceeding any threat posed by well-capitalized stablecoins.
The selective focus on stablecoins becomes even clearer when examining which types face the harshest restrictions. Regulators distinguish between centralized stablecoins (like USDC or USDT) and decentralized stablecoins (like algorithmic protocols). The stated concern is stability, yet the true concern is controllability. A centralized stablecoin issued by a traditional financial institution can be frozen, its transactions monitored, and its operations shut down by regulators. Decentralized alternatives are far more resistant to government intervention, making them profoundly threatening to financial regulatory frameworks built on state authority.
The Reserve Requirement Question
One of the most revealing aspects of emerging stablecoin regulation is the insistence on full or near-full reserves backing these instruments. This requirement, while superficially reasonable for protecting consumers, actually constrains stablecoin utility and growth. A digital currency backed 100 percent in reserve by dollar assets is, in essence, a digitized version of existing dollar holdings. It solves technical problems but does nothing to alter the fundamental monetary system or challenge dollar dominance.
The regulatory insistence on reserves also serves another purpose: it ensures that stablecoin issuers must continuously purchase and hold dollar-denominated assets, thereby supporting demand for dollars and Treasury securities. From a monetary policy perspective, this requirement indirectly props up the dollar’s value and the U.S. government’s ability to borrow cheaply. It is a subtle but profound regulatory choice that demonstrates how digital asset regulation serves broader financial policy objectives.
What True Consumer Protection Would Look Like
The Standards We Actually Apply Elsewhere
To truly understand the regulatory agenda, consider what consumer protection standards would look like if applied consistently. In traditional finance, most deposit insurance protects accounts up to $250,000, with the remainder exposed to institutional solvency risk. Securities regulations focus on disclosure and fraud, not on preventing investment losses. Insurance regulations require solvency reserves but do not prohibit the sale of risky products to informed consumers.
If stablecoins faced these same standards rather than the unique restrictions imposed upon them, the regulatory landscape would look radically different. Issuers would need basic licensing and regular audits. There would be disclosure requirements and restrictions on marketing to unsophisticated investors. Custody arrangements would be transparent and subject to standard financial institution oversight. But stablecoins could operate, scale, and fulfill their economic function without facing de facto prohibition.
The Alternative Framework
A genuinely protective regulatory approach would also recognize the consumer benefits that stablecoins provide. For the estimated 1.7 billion unbanked and underbanked people globally, stablecoins offer access to low-cost financial services, price stability, and freedom from currency devaluation. Citizens in nations with weak currencies or unstable governments can use stablecoins to preserve wealth and conduct commerce. These benefits are not theoretical—they are measurable improvements in financial welfare that benefit billions of people in developing economies.
Yet regulatory frameworks consistently dismiss or ignore these benefits while hyperventilating about hypothetical risks. This asymmetric approach reveals that consumer protection is not the actual priority. If it were, regulators would weigh the genuine benefits to emerging market populations against theoretical risks to financial stability in wealthy nations. The fact that they do not suggests something else drives the regulatory agenda.
The International Dimension: Protecting Financial Power
How Regulation Perpetuates Asymmetric Advantages
The globalization of stablecoin regulation further clarifies the true motivation. Wealthy nations with strong currencies and established financial infrastructure face the strongest regulatory pressure to restrict stablecoins. Meanwhile, the same regulators tacitly permit (or actively encourage) the development of central bank digital currencies (CBDCs) in those wealthy nations. This is not a contradiction—it is strategic consistency.
Governments intend CBDC development to preserve their control over the monetary system while replicating the efficiency benefits of blockchain technology. However, CBDCs remain fundamentally state-controlled, compatible with existing sanctions regimes, and designed to maintain capital controls. They pose no threat to monetary sovereignty or financial hegemony. Conversely, stablecoins—particularly those issued by private entities or operating on truly decentralized networks—represent genuine threats to this carefully constructed system.
Developing Nations and the Real Stakes
For developing economies, the regulatory crackdown on stablecoins carries profound implications. Many nations have weak currencies subject to periodic collapse, unstable governments, and limited access to international capital markets. Stablecoins offer these populations a technological pathway to financial security and international commerce that bypasses the existing infrastructure controlled by wealthy nations.
By pushing for global restrictions on stablecoins, wealthy regulators effectively close off this escape hatch. They force developing nations into continued dependence on dollar-denominated finance, subject to U.S. sanctions, vulnerable to currency devaluation, and constrained by the limitations of existing banking infrastructure. The regulatory narrative emphasizes financial stability, but the practical effect is to perpetuate financial inequality and monetary colonialism. Developing nations cannot build independent financial infrastructure because wealthy nations’ regulators have declared stablecoins too dangerous to permit.
The Path Forward: Regulatory Capture and Market Evolution
The Emerging Reality
Despite regulatory hostility, stablecoin development continues. Cryptocurrency markets have proven remarkably resilient to prohibition, with activity migrating to jurisdictions with friendlier regulatory environments or shifting to decentralized protocols that operate without relying on centralized intermediaries. As this shift occurs, the very regulatory frameworks designed to prevent it become increasingly obsolete.
The most likely future involves a divergence between developed markets and emerging markets. Wealthy nations will maintain tight controls on stablecoins, potentially succeeding in limiting their role in domestic finance. However, they cannot prevent stablecoin adoption elsewhere. As digital currency infrastructure develops in Asia, Africa, and Latin America, these regions will create parallel financial systems less dependent on dollar intermediation. The practical effect will be a gradual erosion of dollar dominance, exactly what regulation was intended to prevent.
The Illusion of Control
This outcome reveals a fundamental regulatory miscalculation. Policymakers believed they could suppress stablecoins through restrictive regulation, preserving dollar hegemony indefinitely. However, monetary systems and financial infrastructure are not static. Technology enables alternatives, and regulatory pressure to those alternatives in wealthy nations simply accelerates their adoption elsewhere. The regulatory crackdown, rather than preventing stablecoin adoption, may actually accelerate the very outcome it was designed to forestall.
Conclusion
Stablecoin regulation is not fundamentally about protecting consumers from fraud or volatility. These concerns serve as convenient justifications, but they mask the true driver of regulatory policy: the preservation of the U.S. dollar’s role as the world’s dominant reserve currency and the broader financial system built upon that dominance. The selective nature of regulatory enforcement, the inconsistency with standards applied elsewhere, and the deliberate handicapping of decentralized alternatives all point toward a regulatory agenda focused on maintaining monetary sovereignty and financial hegemony.
Understanding this reality does not make stablecoin regulation illegitimate. Governments have legitimate interests in preserving financial stability and protecting their monetary systems. However, the current regulatory approach obscures these interests behind a consumer protection narrative, preventing honest debate about the genuine trade-offs involved. Some level of stablecoin restriction may be justified to preserve financial stability, but if that is truly the goal, policymakers should say so explicitly rather than hiding behind spurious claims about protecting retail investors.
The future of digital currency regulation will ultimately depend on whether wealthy nations can reconcile their interest in preserving dollar dominance with the reality that blockchain technology and decentralized finance offer genuine benefits to billions of people in developing economies. If they cannot find this reconciliation, they will face an outcome that no amount of restrictive regulation can prevent: the gradual, inevitable emergence of alternative financial infrastructure operating beyond their control.
Frequently Asked Questions
Q. Are stablecoins actually safe for consumers?
Yes, well-designed and properly regulated stablecoins can be quite safe, particularly when backed by substantial reserves and subject to regular audits. However, the regulatory narrative often conflates the specific risks of individual stablecoins with broader concerns about maintaining monetary sovereignty.
Q. Could stablecoins really threaten financial stability?
Stablecoins could potentially pose systemic risks if they achieved massive scale while remaining poorly capitalized or subject to bank runs. However, financial stability concerns are easily addressed through reserve requirements, disclosure standards, and redemption safeguards
Q. Why do emerging markets care about stablecoins?
In many developing nations, the domestic currency is subject to inflation, devaluation, and capital controls. Stablecoins provide citizens with access to stable stores of value and the ability to conduct international commerce without relying on banks or subject to government financial restrictions.
Q. What is the difference between stablecoins and Central Bank Digital Currencies?
Both stablecoins and CBDCs use blockchain technology or similar systems for efficient digital payments. However, CBDCs remain under direct government control, compatible with existing capital controls and sanctions, and designed to maintain state authority over monetary systems.
Q. Could stablecoin regulation damage the dollar’s dominance long-term?
Ironically, yes. By pushing stablecoin development and adoption to unregulated jurisdictions and decentralized protocols, restrictive regulation may accelerate the very shift away from dollar dominance it was intended to prevent.
